Latest news
- Details
- Hits: 26
Why Now Is the Time to Review Your Options
An empty property can quickly become an expensive property. Whether you're between tenants, waiting for refurbishment work to finish or simply unsure what to do next, a period without rental income brings its own costs and responsibilities.
With the Government recently announcing changes to its powers over long-term empty homes, there is another reason for property owners to review their plans this autumn.
What are Empty Dwelling Management Orders?
On 27 September, the Government announced reforms to Empty Dwelling Management Orders (EDMOs), an existing legal mechanism allowing councils to take over the management of qualifying empty properties and bring them back into occupation, while ownership remains with the owner.
The proposed changes include reducing the qualifying vacancy period from two years to six months and simplifying the application process.
These changes do not mean councils can automatically take over any property that has been empty for six months. However, they highlight the importance of keeping properties properly maintained and having a clear plan for their future.
The hidden costs of leaving a property empty
Lost rental income is the most obvious financial consideration, but it isn't the only one.
Council tax, service charges, utilities and maintenance costs may continue during a vacancy. Insurance policies can also impose specific conditions on unoccupied properties, so landlords should check their cover carefully.
There are practical considerations, too. Without regular inspections, problems such as leaks, damp or heating faults can go unnoticed and potentially become more expensive to resolve.
If refurbishment work is delaying a new tenancy, it is worth reviewing which improvements are essential and whether the property could be brought back to market sooner.
Is your property ready to let?
Before advertising, landlords should ensure their property is safe, compliant and presentable.
A useful starting checklist includes:
● Checking relevant gas and electrical safety requirements.
● Confirming EPC status and applicable energy-efficiency requirements.
● Ensuring required smoke and carbon monoxide alarms are installed.
● Addressing essential maintenance and repairs.
● Arranging cleaning and preparing the property for photographs and viewings.
● Setting a realistic rental price based on comparable local properties.
An experienced letting agent can help identify outstanding requirements and advise on preparing the property for prospective tenants.
Could professional letting support help?
Managing a rental property involves more than finding someone to occupy it. Referencing applicants, arranging tenancy documentation, collecting rent and coordinating maintenance can all demand considerable time.
A letting agent can provide support ranging from tenant-finding and tenancy setup to fully managed services covering ongoing tenant communication, rent administration and maintenance coordination.
The appropriate level of support depends on your circumstances, although landlords should remember that appointing an agent does not remove their legal responsibilities.
Letting or selling: What's right for your property?
Not every vacant property needs to return to the rental market.
Consider the likely rental income against ongoing costs, the investment required to prepare the property, your intended ownership timeframe and how much involvement you want in managing a tenancy.
For some owners, finding a new tenant is the natural next step. Others may prefer professional management or decide that selling better suits their plans.
David Harris & Co are here to help you
At David Harris & Co we see daily the difference that accurate local advice makes. Whether you are an established landlord looking for an extra helping hand or making your way into the rental sector, the autumn market offers genuine choice. Ready to explore Finchley’s property market? Contact David Harris & Co for expert advice and a stress-free experience. Call us on 0208 346 9122 to get started. Let’s make Finchley your next home.
- Details
- Hits: 102
For the past two years, buying in Finchley has been an exercise in patience. Borrowing costs stayed stubbornly high, sellers held out for the prices they remembered from 2021, and a lot of would-be buyers simply waited to see what happened next.
That standoff has largely resolved itself — and it has resolved in the buyer's favour. Prices across Barnet have eased, the number of homes on the market is the highest it has been in over a decade, and one of the largest regeneration schemes North London has seen in years has just been given the green light half a mile from Finchley Central.
None of that makes autumn a guaranteed bargain. But it does make it a market where a well-prepared buyer has genuine leverage, which has not been true for some time. At David Harris & Co, we are here to ensure you use every advantage you can in the current market.
What the numbers actually show
The average house price in Barnet was £604,000 in June 2026, down 2.9% on the year before, according to ONS and HM Land Registry figures. That is a slightly steeper fall than London as a whole, where the average sat at £554,000, down 2.5%.
Zoom into Finchley itself and the picture is more granular. Land Registry data compiled by Rightmove puts the overall average sold price in Finchley at around £653,000 over the past twelve months — roughly 4% below the previous year and about 7% below the 2021 peak. Break that down by type and the spread is wide: flats averaged around £434,000, terraced houses around £749,000, and semi-detached homes around £942,000. In North Finchley, where the overall average is closer to £612,000, flats sold for around £384,000 and semis for around £921,000.
Those gaps matter more than the headline. A 3% borough-wide fall tells you very little about what a three-bed semi off Nether Street will actually cost you. Local sold-price evidence, street by street, is doing the real work.
Choice is the story this autumn
The more significant shift for buyers is supply. Rightmove reported in August that London had the largest choice of homes available to buy since 2010, with average asking prices for newly listed London homes down 3.1% in the month — the sharpest fall of any region.
More stock means more time. It means second viewings without the pressure of a sealed-bid deadline. It means asking for a survey and acting on what it finds. And it means the gap between asking price and sold price is worth taking seriously: in a market this well-supplied, the first figure is an opening position, not a valuation.
The Great North Leisure Park factor
In May, the Mayor of London approved Arada London's redevelopment of the Great North Leisure Park, overturning Barnet Council's earlier refusal. The scheme brings almost 1,500 homes across 20 buildings, 25% of them affordable, alongside a new two-storey leisure centre, a sports pavilion beside Glebelands playing fields, and more than 4,000 sq m of public realm on what is currently an eleven-acre expanse of surface car park.
For buyers, this cuts two ways and it is worth being honest about both. Replacing a car park with a proper leisure centre and landscaped streets is a clear long-term amenity gain for surrounding streets. At the same time, 1,500 new homes arriving over the coming years is a meaningful addition to local supply, and construction on a site that size is not a quiet neighbour.
Neither effect lands this autumn. But if you are buying within walking distance of the site, it belongs in your thinking about the next five to ten years.
Borrowing: the part that can still move
The Bank of England held the base rate at 3.75% on 30 July, on a 6–3 vote, with three members preferring a rise. The next decision comes on 17 September. Fixed mortgage pricing has moved in both directions this summer — several lenders raised rates in July, then trimmed them again through August as competition returned.
The practical lesson is that fixed rates do not simply track the base rate, and they can turn quickly. If you are buying this autumn, get an agreement in principle early and keep it under review rather than assuming today's pricing will still be there in November.
What to look for this autumn in Finchley
● Sold prices, not asking prices. Ask what comparable homes on that street have actually completed at in the last six months.
● Time on the market. A property that has been listed since spring may have room to negotiate — or a problem worth identifying.
● Northern Line reality. Finchley Central, East Finchley and West Finchley are not interchangeable on a wet Monday morning. Walk the route at commuting time.
● Period semi versus newer flat. The two behave very differently in a softer market. Houses in established residential pockets have held value more consistently than flats across North London.
● School catchments. Verify current boundaries directly with Barnet, not from a listing. They change.
● Lease length and service charges on any flat, and the building's remediation status if it is over 11 metres.
● EPC rating. With efficiency standards tightening, a D or E rating is a future cost worth pricing into your offer.
A cooler market rewards preparation
Softer prices and greater choice do not remove risk — they redistribute it. The buyers who do well this autumn will be the ones who know what a fair price looks like on a specific street, who have their finance arranged before they offer, and who are willing to walk away.
If you are weighing up a move in N2, N3 or N12 this autumn and want a straight answer on what a particular street or property type is genuinely worth right now, the team at David Harris & Co have been working these postcodes for years and are always happy to talk it through.
Contact Us Today
Ready to explore Finchley’s property market? Contact David Harris & Co for expert advice and a stress-free experience. Call us on 0208 346 9122 to get started. Let’s make Finchley your next home.
- Details
- Hits: 86
When the main provisions of the Renters' Rights Act came into force on 1 May, most of the commentary was necessarily speculative. Nobody knew how tenants would use their new rights, how the tribunals would cope, or which parts of the legislation would prove awkward in daily practice.
Four months on, some of that is clearer. And the picture for landlords in Finchley and the wider Barnet area is more nuanced than either the alarmist or the reassuring headlines suggested.
The local backdrop is still solid
It is worth starting with demand, because it frames everything else.
Average private rents in Barnet reached £1,945 a month in July 2026, up 3.6% on the year, according to ONS figures. That is comfortably ahead of the London-wide increase of 3.0%. Within the borough, terraced properties saw the strongest growth at 4.0%, and three-bedroom homes rose 3.8% — both consistent with what Finchley agents see on the ground, where family houses within reach of the Northern Line remain the most contested stock.
By property type, average Barnet rents in July stood at around £1,734 for flats and maisonettes, £2,225 for terraced houses, and £2,566 for semi-detached homes. By size, one-bedroom properties averaged £1,496 and three-bedroom properties £2,250.
So the fundamentals have not shifted. What has shifted is the process by which landlords realise that value.
Rent increases: the change that is biting hardest
This is where the practical impact has been sharpest.
Since 1 May, the only valid route to a rent increase is the statutory Section 13 process, once every twelve months, with two months' notice rather than the previous one. Rent review clauses in existing agreements became void on that date, and increases cannot be agreed informally with a tenant outside the statutory process.
The consequence has been a marked rise in tenants exercising a right they always had but rarely used. Property tribunal decisions on rent increases averaged 42 a month across the twelve months to May 2026. That rose to 109 in May and 129 in June.
Two changes explain the shift. Tenants no longer face the implicit risk of a Section 21 notice in response to a challenge, and the tribunal can no longer backdate an increase to the application date — the new rent takes effect only from the date of the decision. With a £47 fee and no downside, challenging has become close to cost-free.
For landlords, the practical implications are concrete. A challenged increase can be delayed by three months or more, and that lost income is not recoverable. Analysis of one sample of tribunal outcomes reported in August suggested a substantial proportion of proposed increases were reduced, often where the landlord had provided limited supporting evidence.
The lesson is not to avoid increasing rent. It is that "costs have gone up" is no longer an argument that works. A Section 13 notice now needs to be backed by comparable local evidence — similar properties, in similar condition, currently letting in N2, N3 or N12 — documented before the notice goes out rather than assembled afterwards if a challenge lands.
Possession: slower, and less forgiving of paperwork
Section 21 is gone. The transitional window closed on 31 July 2026, after which notices served before 1 May could no longer be relied on. All tenancies are now periodic assured tenancies, and possession requires a specific Schedule 2 ground under Section 8.
Two points matter most in practice.
First, the main rent arrears ground now requires three months' unpaid rent rather than two, and the arrears must be at that level both when the notice is served and at the hearing. A tenant who reduces the balance below the threshold before the hearing defeats the ground. Where the shortfall exists only because a Universal Credit housing payment has not yet reached the tenant, that amount is excluded from the calculation.
Second, the court cannot make a possession order if the deposit has not been properly protected in an approved scheme. This is not new advice, but it is now a hard gate on your ability to recover the property.
More cases are being contested than under the old regime, and possession timelines have lengthened accordingly. Acting early on arrears, and documenting every communication, matters more than it used to.
The paperwork that catches people out
Landlords were required to serve existing tenants with the Renters' Rights Act information sheet or a written statement of terms by 31 May 2026. If that slipped in the transition, it is worth resolving now rather than discovering the gap during a dispute.
Also worth checking across a portfolio: rent in advance is banned for new tenancies from 1 May, rent periods are capped at one month, and consent for a tenant to keep a pet cannot be unreasonably refused. Knowingly or recklessly misusing a possession ground has been added to the offences for which the First-tier Tribunal can impose a rent repayment order of up to two years' rent.
What is still coming
The Act rolls out in phases, and the next one is close. The PRS database begins a regional rollout from late 2026, with mandatory landlord and property registration and an annual fee to follow. The PRS Landlord Ombudsman, which all private landlords must join, is expected around 2028. The extension of Awaab's Law to the private sector remains subject to consultation, and the modernised Decent Homes Standard has a long-term date of 2035.
Separately, the deadline for energy efficiency is now fixed. The Warm Homes Plan, published on 21 January 2026, confirmed that privately rented homes in England and Wales must reach EPC C or equivalent by 1 October 2030. The earlier phased approach, which would have applied to new tenancies from 2028, has been dropped in favour of a single date. Compliance will be measured against reformed EPC metrics rather than today's single rating.
Given the age of much Finchley stock — a large share of it Victorian and interwar — this is the item most likely to require capital planning rather than administrative tidying.
The practical position
The landlords having the easiest time of it four months in are not the ones with the largest portfolios. They are the ones with good records, evidenced rent decisions, and tenants who have no particular reason to make life difficult.
That last point is doing more work than it used to. In a regime where a tenant can delay an increase for a quarter at a cost of £47, the value of a tenancy that is running well has gone up considerably.
If you own rental property in Finchley or the surrounding N postcodes and want to review where your tenancies stand — evidence for your next Section 13, compliance across a portfolio, or simply what your property should realistically be achieving now — the lettings team at David Harris & Co are happy to go through it with you.
Contact Us Today
Ready to make a smart move in Finchley’s rental market? Contact David Harris & Co for expert advice and a stress-free experience. Call us on 0208 346 9122 to get started. Let’s make Finchley your next home.
- Details
- Hits: 186
What the N3 and N12 numbers really tell us
Two similar houses can go on the market on the same street in the same week, and one will be sold within five weeks while the other is still sitting there at Christmas. Nothing about the properties explains it. Almost everything about the asking price on day one does.
That gap — currently around 36 days for well-priced homes against well over 100 for those launched above value — is the single most useful thing a Finchley seller can understand about this market. Here is where the rest of the numbers sit.
Where prices stand in N3 and N12
Average sold prices in N3, covering Finchley Central and Church End, are around £788,000 over the past 12 months according to Zoopla's Land Registry data — a figure that reflects Finchley's enduring premium within the North London market.
In N12, North Finchley, the overall average is approximately £623,000. Broken down by property type: flats average £377,000, terraced homes £729,000, and semi-detached properties £943,000.
The averages hide more than they reveal
At first glance, that £165,000 gap between N3 and N12 looks like a straightforward statement about desirability. It isn't.
Look again at the N12 breakdown. Semi-detached homes in North Finchley are averaging £943,000 — comfortably above the overall N3 average. What pulls the N12 figure down is the mix of stock, not the quality of it. N12 simply contains a far higher proportion of flats, and at an average of £377,000 they weigh heavily on the postcode-wide number.
This matters practically. If you own a semi in N12 and you benchmark your expectations against "the N12 average," you will undervalue your home by a wide margin. If you own a flat in N3 and you do the same in reverse, you will price yourself into a very long summer,autumn and maybe even winter. Postcode averages are a starting point for conversation, not a valuation.
The wider backdrop
Across Finchley more broadly, asking prices have softened by around 2.4% over the past six months. That is a meaningful signal: buyers hold more negotiating power than they did in 2022–23, and initial pricing carries more consequence than it did then.
Nationally, UK house prices are up 1.5% year-on-year at £271,900 on Zoopla's latest data, though London and the south are broadly flat or marginally down, with the stronger growth concentrated in the north.
On borrowing, average two-year fixed mortgage rates stand at around 5.65% according to Moneyfacts' latest data, easing slightly from the spring peak after reductions from major lenders including Halifax and HSBC. Small movements at that level still change what a buyer can offer, which is part of why negotiation has become more deliberate.
On the rental side
Demand across N3 and N12 remains strong, driven by proximity to Finchley Central and West Finchley stations and Finchley's established appeal to professional tenants — a pattern that has held steady through several shifts in the sales market.
Why Finchley's fundamentals hold
What distinguishes Finchley is not one factor but the combination of several. Northern line access from both Finchley Central and East Finchley puts the City and West End within 30 minutes. The schools — Christ's College, Finchley Catholic High, and a strong primary catchment across N3 and N12 — continue to draw family buyers from across London.
Then there are the things that don't appear in any dataset: Cherry Tree Wood, Victoria Park and the green space around East Finchley; the independent café culture along North Finchley High Road and Whetstone; the Waitrose anchor on Ballards Lane. This is the daily liveability that tends to hold value through different market cycles, and it is why buyers who come to view so often end up staying.
If you are weighing up a move this year, the most valuable half-hour you can spend is on getting the launch price right for your specific property — not your postcode's average. At David Harris & Co, we are always happy to assist you.
Contact Us Today
Ready to explore Finchley’s property market? Contact David Harris & Co for expert advice and a stress-free experience. Call us on 0208 346 9122 to get started. Let’s make Finchley your next home.
- Details
- Hits: 186
Here's how to actually check.
Choosing an estate agent is one of the few significant financial decisions most people make almost entirely on impression. You invite two or three agents round, they each spend forty minutes in your home, and at the end of it you pick one — largely on the basis of how they came across and what number they wrote down.
The difficulty is that the qualities that matter most in an agent are the ones you cannot observe at a valuation appointment. Whether they price honestly rather than flatteringly. Whether the sales they agree actually complete. Whether their previous clients would use them again. Every agent will assure you on all three counts, and none of those assurances cost anything to make.
Which is why independent measurement matters more here than in almost any other service you buy.
What gets measured when the agent isn't the one keeping score
The Trusted Agent awards are compiled by ViewAgents, an independent benchmarking platform that analyses performance data and customer feedback from thousands of estate agents across the UK. Crucially, the assessment is not a submission process where agencies put forward their best work. It draws on five areas:
● Sales and lettings performance
● Customer reviews across Google, Facebook, Trustpilot and Feefo
● Time to sell and let
● Fall-through rates
● Overall customer satisfaction
Two of those deserve more attention than they usually get.
Fall-through rates measure how often an agreed sale collapses before completion. This is the metric no agency advertises, because it exposes the gap between agreeing a sale and delivering one. A collapsed sale is not a neutral event for a seller — it costs weeks or months, often several hundred pounds in wasted legal and survey fees, and it can bring down an onward purchase with it. An agent who agrees sales quickly but loses a high proportion of them will look excellent on a "sold" board and considerably worse in your bank account.
Time to sell and let is the honest counterweight to over-valuation. An agent can win your instruction by suggesting a price nobody will pay, and the cost of that shows up months later. Measuring the days involved makes the practice visible.
Together, these are the numbers that reveal how an agency actually behaves rather than how it presents.
Where David Harris & Co placed
On that independent assessment, David Harris & Co has been awarded Trusted Agent 2026 status, placing the agency in the top 10% of more than 20,000 estate agency offices across the UK, at a national rank of #1,441.
Put the other way round: more than 18,000 offices did not make the list.
Alongside this sits a customer rating of 4.9 out of 5, drawn from 244 verified reviews. The volume matters as much as the score — a handful of glowing reviews tells you very little, while a rating held at that level across 244 of them is considerably harder to arrange.
Why any of this should influence your choice
Awards are easy to be cynical about, and often that cynicism is well placed. The distinction worth drawing is between recognition an agency applies for and recognition derived from data it did not control. The second kind tells you something the first cannot.
For a seller, the practical translation is this: the criteria behind the award are the same criteria that determine whether your own sale goes smoothly. Accurate pricing, realistic timescales, sales that hold together, clients who felt well treated at the end. You are not choosing an agent because they won something — you are choosing them because the thing they won was measured on precisely what you need.
The long view
Most people move several times. The first move is usually a matter of guesswork; you have no basis for comparison and you choose on instinct.
The value of getting it right is that you generally do not have to repeat the exercise. People who find an agent who priced honestly, communicated properly and saw the sale through tend to call the same firm when they buy, when they let, and when their parents or children need to move. Local expertise compounds — an agent who already knows your street, your building's management company and what the flat two doors down actually achieved is starting from a considerably better position than one meeting you for the first time.
Choose well, and your next local estate agent may be the last one you ever need to find.
Contact Us Today
Ready to explore Finchley’s property market? Contact David Harris & Co for expert advice and a stress-free experience. Call us on 0208 346 9122 to get started. Let’s make Finchley your next home.
- Details
- Hits: 395
Headline indices and sentiment surveys tend to tell you where the market has been. To understand where it's actually heading, you need to look at transactions and where capital is being deployed. That's the lens this piece takes.
The underlying story is a simple one: demand for London hasn't gone away. The city's pull as a global centre for talent, capital and employment remains intact. The complexity lies in how that demand is being expressed — and increasingly, that's not through traditional ownership. If you want to stay up to date with how the shaping up, David Harris & Co is here for you.
Ownership Demand Hasn't Disappeared — It's Being Priced Out
The aspiration to own a home in London is still very much alive. What's changed is people's ability to act on it. Last year, 48,820 mortgage loans were granted to first-time buyers in the capital — the highest annual total since the Global Financial Crisis, if you set aside the brief spike during the stamp duty holiday. The driver was straightforward: mortgage rates eased through 2025, and affordability improved as a result.
That relationship cuts both ways. Rates fell for most of 2025 before climbing again in early 2026, and buyer activity responded almost immediately in both directions. Industry figures point to just how fine the margins are here — even a modest 15 basis point rise in mortgage rates can be enough to tip a buyer past an affordability threshold. The consensus among agents is that this isn't a fading desire to own; it's renting by necessity rather than choice, and as soon as the pressure eases even slightly, first-time buyer activity picks back up.
That reframes the current softness in the for-sale market. It looks less like structural decline and more like demand that's been pushed back, waiting for borrowing costs to settle and for institutional rental stock to be priced more accessibly. The tension for the market is that rising house prices help viability and delivery, but simultaneously make the affordability problem worse — both need managing at once.
The Rental Market Is Normalising, Not Collapsing
After the exceptional rental growth of 2022 and 2023, London's rental market has settled into a calmer phase. This is best understood as a return to more typical conditions rather than a market in trouble.
Affordability remains the central issue. HomeLet data puts the gross rent-to-income ratio for new London tenancies at 38.3% — still high by historical standards. But that headline figure hides a growing split: conditions are easing for higher earners while pressure continues to build for those on lower incomes. Renting isn't purely a financial decision either — for higher earners who move frequently for work, it's often a deliberate choice for flexibility.
The strain is visible in how tenants are behaving: more people relocating to cheaper areas, more sharing of properties, and more downsizing.
At the same time, structural pressure on landlords is mounting. The Renters' Rights Act, introduced in May, along with tightening energy efficiency requirements running through to 2030, is adding to costs and compliance obligations. Private landlords are leaving the market in meaningful numbers, and institutional build-to-rent delivery isn't yet scaling fast enough to replace that stock. The net effect is a market where falling demand and shrinking supply are broadly cancelling each other out, keeping things tighter than the headline demand figures alone would suggest.
The scale of landlord exit is significant. UK Finance figures show outstanding buy-to-let mortgages have fallen by roughly 643,000 since 2016. The NRLA's most recent landlord survey found that 40% of members are weighing up a sale within the next two years, and Zoopla estimates that 31% of London homes listed for sale at the end of 2025 had previously been rented out.
Institutional supply isn't yet closing that gap. London's multifamily sector added 31,004 units between 2020 and 2025, with 4,355 of those delivered in 2025 alone. CBRE's forecast puts future delivery at around 4,000 units a year through to 2030 — below the 5,100 average seen over the previous five years. Alternative products remain small in scale too: the UK had roughly 11,000 operational co-living beds in 2025, mostly concentrated in London, while purpose-built student accommodation continues to face its own supply-demand imbalance.
What's actually needed to close the rental affordability gap comes down to a fairly short list: affordable housing from registered providers, single-family build-to-rent in outer London, and amenity-light, mid-market multifamily stock.
London's Employment Base Remains the Foundation
International demand for London Living property looks quite different than it did a decade ago. Buyer interest is no longer concentrated in just two or three geographies but is spread more broadly, which gives the market a useful cushion — when one region slows, others tend to pick up the slack, particularly valuable during periods of wider economic or geopolitical uncertainty.
Underpinning all of this is London's role as the country's primary employment hub. Office-based employment in the capital grew by 28.6% cumulatively between 2016 and 2025, outpacing many European and global peer cities, with a further 8.1% cumulative growth forecast through to 2030. Population growth, rising incomes and a resilient labour market continue to drive housing need across every tenure and price point.
Bulk Sales Are Where Institutional Demand Shows Up First
One of the clearest signs of institutional capital absorbing surplus stock is in bulk sales — where developers sell off completed but unsold homes in single transactions rather than through the usual drip-fed sales process.
Molior data shows 3,648 complete and unsold new-build homes across London in Q1 2026, equivalent to 39% of the annual sales rate — the second-highest proportion on record. Buyers of this stock are a mixed group: local authorities looking to cut temporary accommodation costs, registered providers, for-profit registered providers, and opportunistic institutional investors.
The shift towards bulk purchasing is measurable. Of new homes sold over the 12 months to Q1 2026, 58% went to companies via build-to-rent, block sales, other bulk deals or affordable-tenure switches, up from 52% in 2024. Within that, bulk deals excluding build-to-rent rose to 7% of sales, up from 4%, and homes switching to affordable tenure climbed to 15%, up from 11%. Traditional open-market sales to individual buyers fell over the same period, from 34% to 30%.
The turnkey sale of Barratt London and LRC's Eastman Village scheme in Harrow is a useful real-world example — completed build-to-rent stock transferring in one transaction to long-term institutional ownership, freeing the developer to reinvest in new delivery. Industry sentiment suggests this kind of activity is accelerating rather than slowing, with completed stock increasingly being absorbed by local authorities, registered providers and opportunistic buyers taking advantage of where the cycle currently sits.
What This Means Going Forward
The desire to live in London hasn't weakened — but affordability and market dynamics continue to reshape how that demand is met. For-sale supply remains constrained, the rental market is settling from unusually high levels, and affordability continues to shape behaviour across the board.
There is progress on the supply side, but it won't be enough on its own. With borrowing costs still elevated and consumer confidence subdued, some form of demand-side support looks necessary to bring schemes forward at scale. There's also a widening gap between housing policy targets and what the market can realistically deliver, which risks deepening the supply shortfall over time if left unaddressed.
Build costs remain a persistent constraint too — viability, more than anything else, is what limits the pace of delivery in London. Ultimately, demand, capital and delivery are closely linked, and converting underlying desire into deliverable homes will depend on structures like bulk sales, joint ventures, for-profit registered provider models and mid-market rental playing a central role.
Contact Us Today
Ready to explore Finchley’s property market? Contact David Harris & Co for expert advice and a stress-free experience. Call us on 0208 346 9122 to get started. Let’s make Finchley your next home.
- Details
- Hits: 311
Finchley Summer 2026 - What Buyers and Sellers and Need to Know
If you're keeping half an eye on the Finchley property market, you'll know it rarely stands still for long. Here's a grounded look at where things stand right now, and what it means whether you're buying, selling, letting or renting in the local area. David Harris & Co are on hand to assist you.
What Properties Are Actually Selling For
In N3 (Finchley Central and Church End), the average sold price over the past 12 months sits at around £788,000, according to Zoopla Land Registry data. It's a figure that underlines just how much of a premium Finchley continues to command within North London.
Move north into N12 and the picture shifts, as you'd expect with a wider mix of property types. The overall average here is closer to £623,000. Break that down by property type and flats are averaging £377,000, terraced homes £729,000, and semi-detached properties £943,000 — a reminder that "average" figures only tell part of the story, and the type of home you're buying or selling matters just as much as the postcode.
A Gentle Cooling in Asking Prices
Across Finchley more broadly, asking prices have eased by around 2.4% over the past six months. That's not a dramatic shift, but it does matter: it suggests buyers currently have a little more room to negotiate than they did back in 2022-23. For sellers, it also reinforces something worth taking seriously — getting the initial price right from day one is more important now than it's been in some time.
The National Backdrop
Zooming out, UK house prices nationally are up 1.5% year-on-year, reaching an average of £271,900 as of June 2026 (Zoopla). London and the south, however, are largely flat or nudging slightly downward, while northern regions are seeing noticeably stronger growth. It's a divergence that's worth bearing in mind when national headlines don't quite seem to match what's happening on your own street.
On the mortgage side, average two-year fixed rates are hovering around 5.65%, according to Moneyfacts data from early June 2026. That's a modest step down from the spring peak, helped along by rate reductions from major lenders including Halifax and HSBC.
Renting in Finchley: Demand Holds Firm
For landlords and tenants, rental demand across N3 and N12 remains robust. Much of that comes down to location — proximity to Finchley Central and West Finchley stations continues to make the area genuinely attractive to professional tenants, and that appeal shows little sign of fading.
Speed Matters More Than Ever for Sellers
Perhaps the clearest signal in the current data is around timing. Homes that are priced accurately and properly presented from the outset are typically selling within around 36 days. Those listed above their true market value, by contrast, are often sitting for well over 100 days — and frequently end up reducing anyway, having lost both momentum and buyer confidence along the way.
Why Finchley Continues to Hold Its Appeal
No single factor explains Finchley's enduring pull — it's really the combination. The Northern line, accessible from both Finchley Central and East Finchley, gets residents into the City or West End in under half an hour, which continues to draw commuters and families alike.
Schools remain a significant part of the story too. Christ's College and Finchley Catholic High, alongside a consistently strong primary catchment across N3 and N12, keep pulling family buyers in from across London.
Then there's the everyday liveability: Cherry Tree Wood, Victoria Park and the green spaces around East Finchley give the area a breathing room that's increasingly rare this close to the city. Add in the independent café scene along North Finchley High Road and Whetstone, plus the Waitrose on Ballards Lane, and you have the kind of daily convenience that tends to hold its value regardless of where the wider market is heading.
Contact Us Today
Ready to explore Finchley’s property market? Contact David Harris & Co for expert advice and a stress-free experience. Call us on 0208 346 9122 to get started. Let’s make Finchley your next home.
- Details
- Hits: 2285
What Could It Mean for Finchley Property Owners?
One of the largest regeneration projects proposed for North London has taken a significant step forward following the approval of plans to redevelop the Great North Leisure Park in Finchley.
After initially being rejected by Barnet Council, the scheme was approved by the Mayor of London's office in May 2026. The project will transform the existing leisure park into a major mixed-use neighbourhood featuring nearly 1,500 new homes, extensive green space and modern community facilities.
For local homeowners, landlords and prospective buyers, the decision raises an important question: what impact could this have on the Finchley property market?
At David Harris & Co, we know the local area well, and we are keen to provide you with as much guidance and support as we can to help you make a smart move.
What Is Being Built?
The redevelopment will replace the current car-dominated leisure park with a new residential and community-focused development.
The plans include:
● 1,485 new homes.
● 25% affordable housing.
● A new leisure centre.
● An outdoor lido.
● A new sports pavilion.
● More than 2.5 hectares of landscaped green space.
● Children's play areas.
● Green roofs and ecological corridors.
● An on-site employment and training centre known as the Arada Academy.
The existing leisure centre will remain open until the replacement facility has been completed, helping to minimise disruption for local residents.
Construction is expected to begin in 2027.
Why Was the Original Refusal Overturned?
Barnet Council originally rejected the proposals, citing concerns about the scale and density of the development, particularly the inclusion of towers reaching up to 25 storeys.
However, City Hall concluded that the benefits outweighed those concerns.
The Mayor's office argued that underused brownfield sites such as Great North Leisure Park are exactly the type of locations that should accommodate future housing growth. The alternative, according to planners, would be increased pressure on more sensitive areas, including parts of London's Green Belt.
The scheme was also praised for its design approach, environmental credentials and community facilities.
What Could This Mean for Local Property Values?
While it is impossible to predict future house prices with certainty, large-scale regeneration projects often influence local property markets in several ways.
The most obvious change will be the substantial increase in housing supply. Nearly 1,500 new homes is a significant addition to the Finchley housing stock and will create a much larger residential community in the area.
At the same time, new developments often bring improved infrastructure, better public spaces and enhanced local amenities, all of which can increase the attractiveness of a neighbourhood.
The new leisure centre, lido, green spaces and improved public realm could make this part of Finchley more appealing to buyers and tenants alike.
For landlords, improved amenities can help support long-term rental demand, particularly among younger professionals and families seeking access to modern facilities.
A Shift Towards Higher-Density Living
One of the most noticeable impacts will be the changing character of the local area.
Finchley is traditionally associated with lower-rise housing and suburban streets. The new development introduces a much higher-density model, with 20 residential buildings and heights reaching up to 25 storeys.
Supporters argue that this is necessary to help address London's housing shortage, while critics remain concerned about the scale of the project and the effect it may have on the area's character.
Regardless of individual views, the development represents a significant change in how parts of North London may evolve in the coming years.
Environmental and Community Benefits
A key feature of the scheme is its focus on sustainability and community infrastructure.
Plans include a 150% biodiversity net gain through new planting, ecological corridors and green roofs. There will also be stronger links to nearby open spaces, including the Glebelands Nature Reserve and surrounding playing fields.
The Arada Academy will provide construction and employment training for local residents, including military veterans, with more than 80 learners expected to benefit each year during the construction phase.
Additional bus services are also planned to help support the growing population expected to live in the area.
Looking Ahead
The approval of the Great North Leisure Park redevelopment marks one of the most significant planning decisions in Finchley for many years.
Whether viewed as a solution to London's housing shortage or a major change to the local skyline, the project will undoubtedly reshape this part of North London over the coming decade.
For property owners, landlords and prospective buyers, it will be worth monitoring how the development progresses, particularly as construction begins and the wider impact on local demand, amenities and housing supply becomes clearer.
Whatever move you wish to make, David Harris & Co is here for you.
At David Harris & Co, we understand what makes Finchley unique. Whether you’re buying, selling, or renting, our local expertise ensures we can guide you to the best decisions for your needs. Ready to explore Finchley’s property market?
Contact David Harris & Co for expert advice and a stress-free experience. Call us on 0208 346 9122 to get started. Let’s make Finchley your next home.
- Details
- Hits: 283
We know our clients love the service they receive from David Harris & Co. They tell us, they say so in their reviews, and they come back or tell their friends to check us out.
We take immense pride in being the letting agent people trust and recommend in N3, and we promise to keep working hard to ensure you receive the best service at all times.
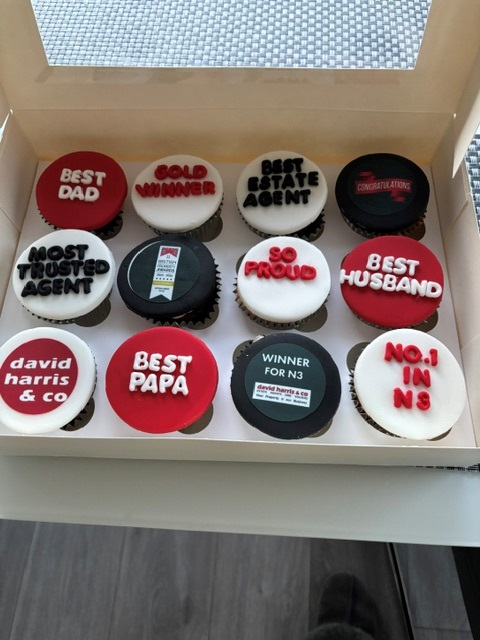
We’re also thrilled to announce we are 2025/26 Gold Award Winners for Letting Agents in N3, at the British Property Awards.